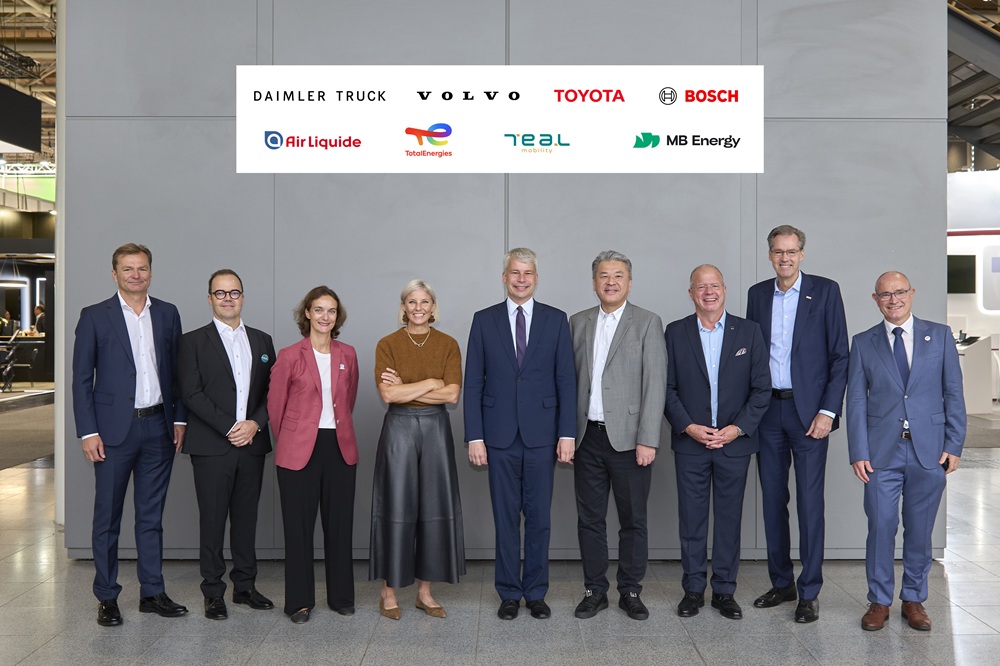
- European Truck and Bus Manufacturers urge infrastructure action.
- Only 2.4% of new trucks are zero-emission.
- Poland, Spain, and Italy remain below 1% adoption.
Infrastructure Delays Threaten the Heavy-Duty Vehicle Transition
European Truck and Bus Manufacturers warned at IAA Transportation 2026 in Germany that delays in charging, energy, and other supporting infrastructure are slowing the shift toward zero-emission heavy-duty vehicles. The European Automobile Manufacturers' Association said the industry's seven major truck and bus manufacturers remain committed to the European Union's carbon dioxide reduction targets and have already developed a broad range of competitive zero-emission vehicles. However, the infrastructure and operating conditions required for large-scale adoption are at least three years behind schedule, producing low and uneven market uptake across Europe and increasing pressure on policymakers to address the gap.
Zero-Emission Truck Adoption Remains Limited
Only 2.4% of new heavy-duty trucks registered in Europe are currently zero-emission, highlighting the substantial distance between present market adoption and the transition required under the 2030 carbon dioxide targets. Adoption varies sharply among major European markets. Zero-emission trucks account for less than 1% of new registrations in Poland, Spain, and Italy, while Germany records 4.3% and France records 2.4%. With 45 months remaining until the 2030 targets, manufacturers argue that current infrastructure deployment and market conditions are not advancing quickly enough to support the required transition.
Charging and Energy Infrastructure Need Faster Deployment
The manufacturers said wider access to charging infrastructure and electricity grids is essential for making zero-emission trucks financially viable for operators. Lower energy costs, carbon dioxide-based road tolls, and supportive government policies were also identified as important conditions for increasing adoption. The industry's position is that vehicle technology is already available, but operators need an effective operating environment in which zero-emission trucks can be deployed economically at scale. The infrastructure shortfall therefore extends beyond vehicle manufacturing and requires coordinated action involving governments, infrastructure providers, energy systems, operators, and other participants across the commercial vehicle value chain.
Manufacturers Seek Review of the 2030 Compliance Timeline
The seven manufacturers called on European and national policymakers to close the infrastructure gap and review the 2030 carbon dioxide compliance timeline. Their concern centers on the relationship between regulatory requirements and actual market conditions. Manufacturers face significant financial penalties if they fail to meet carbon dioxide targets, yet the market conditions required to achieve those targets depend substantially on factors outside their direct control. From the industry's perspective, compliance requirements cannot by themselves create sufficient demand when charging availability, grid access, energy economics, and supportive policy measures remain inadequate across key European markets.
ACEA Warns Against Penalties Without Stronger Market Demand
The European Automobile Manufacturers' Association warned that imposing penalties while market demand remains too weak would not necessarily increase the number of zero-emission trucks on European roads. Instead, ACEA said such penalties could redirect billions of euros away from investment in new technologies and production capacity. That outcome could weaken European manufacturers as competition in global markets intensifies. The manufacturers therefore argue that policy should focus on creating the practical and economic conditions required for operators to adopt zero-emission vehicles, rather than relying primarily on financial penalties when infrastructure and demand remain insufficient.
Industry Impact & Outlook
The infrastructure gap creates a direct challenge for Europe's heavy-duty vehicle transition because manufacturers may have competitive zero-emission products available while operators still face barriers to practical and economical deployment. Faster charging and grid development, improved energy economics, and supportive road-toll and policy frameworks could help narrow the adoption gap before 2030. The issue is particularly significant in markets where zero-emission truck uptake remains below 1%, while higher-uptake markets such as Germany provide evidence of stronger adoption under more developed conditions. The next phase will depend on whether policymakers, infrastructure providers, and the wider value chain can accelerate the conditions needed for commercial-scale deployment.
Frequently Asked Questions
Why are zero-emission heavy-duty vehicle sales still low in Europe?
The main challenge identified by manufacturers is not vehicle availability but insufficient supporting infrastructure and unfavorable operating economics for large-scale deployment. Charging access, electricity-grid availability, energy costs, road-toll structures, and supportive policies all influence whether operators can adopt zero-emission trucks economically. According to the European Automobile Manufacturers' Association, only 2.4% of new heavy-duty trucks registered in Europe are currently zero-emission. Adoption is below 1% in Poland, Spain, and Italy, while Germany reaches 4.3%, demonstrating substantial variation between European markets.
Click above to visit the official source.
Discussion
Join the conversation.